Many small businesses rely on automated bank feeds and simple rules, expecting tidy financials with minimal effort. Feeds are useful, but they are not accounting. They cannot see undeposited funds, do not understand timing differences, and will not test your balances against source documents. If you have ever wondered why your profit and loss swings wildly or why your cash balance never matches the bank, the gap is usually a missing monthly close. This article explains what bank feeds miss, the downstream distortions they create, and a practical close routine that produces reliable numbers lenders, tax preparers, and operators can trust.
What Bank Feeds Miss: Deposits, Timing, and Clearing Accounts
Bank feeds import activity, not business logic. A Stripe or Shopify payout may bundle multiple days of sales, refunds, chargebacks, and merchant fees into a single net deposit. POS systems create daily batches that hit Undeposited Funds before reaching the bank. Payroll platforms combine wages, taxes, and benefits in lump-sum debits. Without matching these items in the general ledger, revenue and fees get smeared. If you plan to outsource part of the close, confirm how a provider such as https://accountinglabs.co/ documents reconciliations and delivers a month-end package with bank recs, AR/AP agings, and adjusting entries.
Consider two common scenarios. A coffee shop runs card sales through a POS that deposits yesterday’s net after interchange fees. If you post the bank line as revenue, fees vanish from expenses and daily sales mix across dates. An e-commerce seller receives a marketplace payout that includes prior-period returns and shipping reimbursements. Without a clearing account to collect gross sales, fees, and timing adjustments, both the income statement and the cash flow statement mislead management.
How Feed-Only Posting Distorts Cash, Margin, and Taxes
Skipping reconciliations leaves cash misstated because the ledger never proves to bank statements. Auto-accepting rules often book inventory purchases to generic supplies, shrinking cost of goods sold and inflating gross margin. Sales tax collected may be coded as income, overstating revenue and creating a hidden liability. Ignoring accounts receivable and accounts payable unintentionally shifts everything to a cash basis, which can move revenue and expenses into the wrong month and alter taxable income. Depreciation and amortization are also absent when no one maintains a fixed asset schedule.
Imagine a contractor who receives a 50 percent deposit on a job with retainage held until completion. Feed-only posting records the bank deposit as revenue, even though half should be recorded as deferred revenue and retained in retainage tracking. Materials bought on account get paid later, yet without an AP entry, nothing hits expenses until the check clears. The result is a lumpy profit story that confuses job costing, misguides pricing decisions, and risks underpayment or overpayment of estimated taxes.
Rebuilding Accuracy: A Practical Clean-Up Sequence
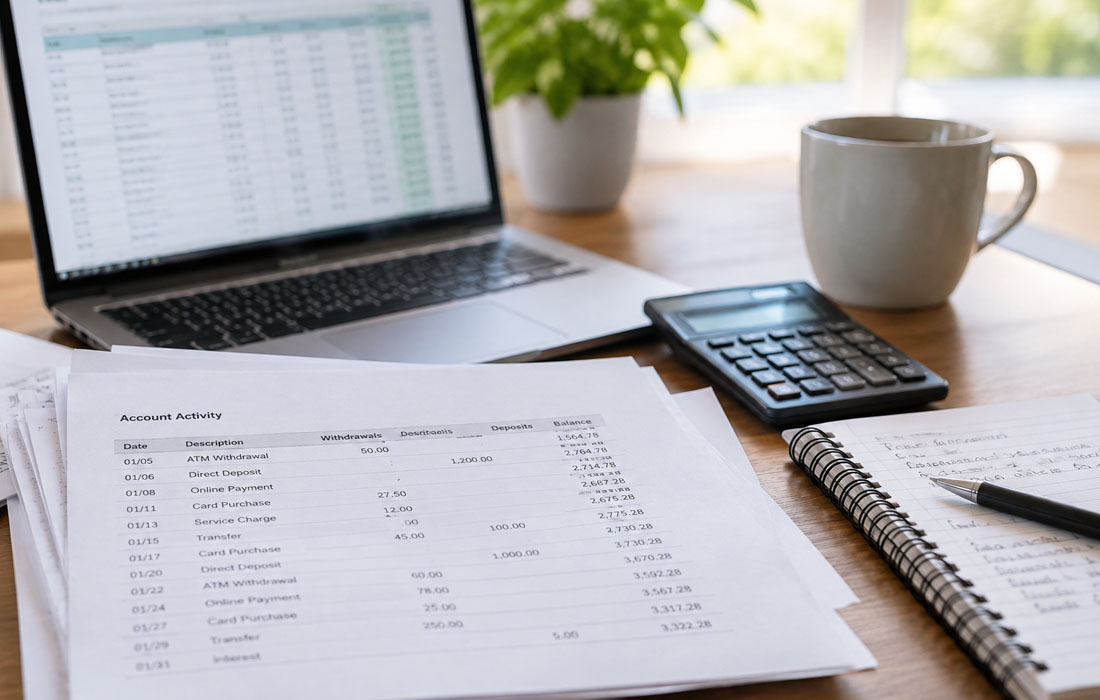
Start with documents, not software. Gather bank and credit card statements, merchant processor reports, payroll registers, sales tax filings, and loan amortization schedules. Lock a clean opening balance date. Reconcile bank and credit card accounts month by month, matching each deposit to sales receipts via Undeposited Funds and each payout to a processor clearing account. Build AR from customer invoices and tie to statements; enter AP from vendor statements and open bills. Replace payroll bank-line guesses with a payroll journal entry that splits gross wages, employer taxes, and benefits to the correct ledger accounts.
Next, true up the trial balance with adjusting entries. Record inventory counts and adjustments, reclassify large equipment to fixed assets, and post depreciation from a maintained schedule. Book prepaids and accruals so expenses land in the right month. Set up deferred revenue for deposits and recognize revenue as milestones are met. Clear suspense and uncategorized expense accounts with documented explanations. Keep a binder close at hand: bank reconciliations, AR/AP aging reports, inventory rollforward, fixed asset register, sales tax tie-outs, and a list of all month-end journal entries.
The Monthly Close: Checklist Items That Create Trustworthy Numbers
A workable monthly close has a repeatable checklist. Reconcile every bank, credit card, and loan account to statements and review reconciliation reports, not just register balances. Confirm clearing accounts, such as merchant processors and payroll liabilities, zero out after posting. Age accounts receivable and follow up on past-due invoices; age accounts payable and flag credits or duplicate bills. Verify sales tax collected matches filed returns and cash remitted. Capture W-9 forms early and mark 1099-eligible vendors to avoid a January scramble. For product businesses, count inventory or run cycle counts and reconcile to cost of goods sold.
Finish with a financial review. Scan the income statement for odd spikes, compare gross margin to recent months, and investigate material variances. Inspect the balance sheet for stale balances, such as old undeposited funds or negative vendor balances. Post recurring entries for depreciation, amortization, and prepaids. Lock the period in your accounting system to protect closed months. Document who prepared each task, who reviewed it, and when exceptions were resolved. These small controls turn raw feeds into managerial accounting you can use to price jobs, forecast cash, and talk to lenders with confidence.
Choosing Workflows: Cash vs. Accrual and DIY vs. Outsourced
Cash basis is simpler to maintain, but it blurs performance when invoices, bills, or inventory matter. Accrual bookkeeping adds AR, AP, and inventory adjustments so revenue and expense reflect when work is performed and goods are delivered. Some firms keep books on accrual for management and convert to cash for tax filing, using book-to-tax adjustments to bridge the methods. The trade-off is effort and expertise: accrual detail improves pricing, gross margin tracking, and lender conversations, but it requires a sturdier close and tighter documentation.
Decide who runs which parts of the workflow. Many owners keep bill approvals and outgoing payments in-house for control while outsourcing reconciliations, payroll entries, and month-end reviews. Ask any external bookkeeper about their close calendar, evidence of reconciliations, AR/AP support, 1099 preparation, and data security. Set segregation of duties where possible: the person reconciling bank accounts should not also release payments. Revisit workflows as volume grows, channels multiply, or sales tax nexus expands. A quarterly CPA review of your trial balance and adjusting entries helps keep tax estimates up to date and prevents year-end surprises.
Reliable financials are built, not scraped from a feed. When deposits tie to sales receipts, clearing accounts zero out, and every statement is reconciled, your income statement, balance sheet, and cash flow begin to tell a coherent story. That clarity lets you spot margin slippage, plan hiring with payroll in view, and approach bankers or investors with confidence. Start with one disciplined month-end checklist, document each step, and protect closed periods. After two or three cycles, the noise fades, and trends emerge. The books stop arguing with the bank, and your decisions start leaning on numbers you can defend.